More Americans Fall Behind on Car Payments as Auto Loan Delinquencies Spike in 2025
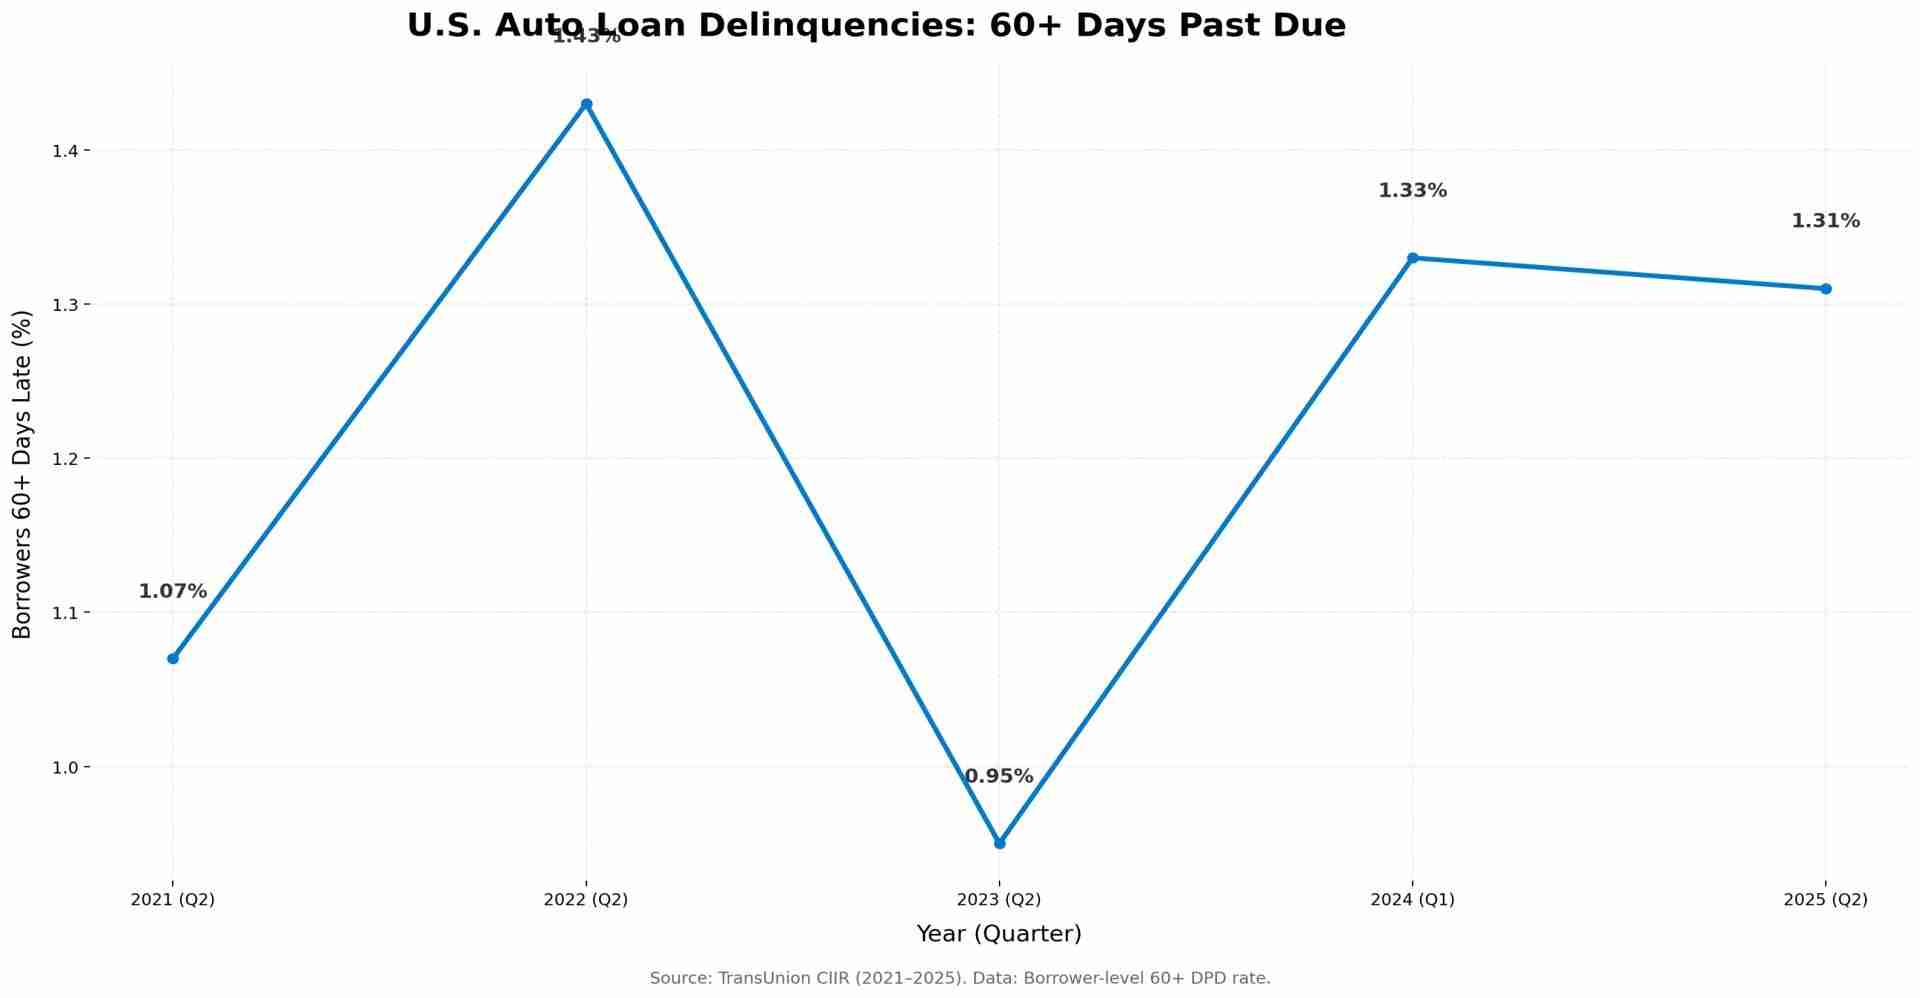
New data shows U.S. auto loan delinquencies climbed to 5.1% in Q1 2025, the highest level in years, driven by high interest rates, elevated vehicle prices and sluggish wage growth — hitting younger borrowers and Southern states hardest.
Key takeaways
- National delinquency: 5.1% of auto borrowers were delinquent on at least one account in Q1 2025 (LendingTree).
- Generational gap: Gen Z 7.5%, Millennials 6.9%, Gen X 4.3%, Baby Boomers 1.9% (LendingTree).
- Late-stage delinquencies: 90+ days past due rose to 0.45%, up 25 basis points month‑over‑month (VantageScore).
- Balances and payments: Average monthly car payment $751 nationally; total U.S. auto loan balances were $1.642 trillion in Q1 2025 (LendingTree, New York Fed).
What the data shows
The number of people missing car payments is rising. LendingTree found 5.1% of auto borrowers were behind on at least one account in the first quarter of 2025 — the highest level in years. State results vary widely, from a low near 3.2% to a high of 9.8% in Mississippi, with Southern states like Louisiana (8.4%) and Georgia (7.8%) also especially stressed.
Why delinquencies are rising
Experts point to several clear drivers: higher interest rates on new and used loans, persistently elevated vehicle prices after pandemic disruptions, and wage growth that has not kept pace with rising living costs. The restart of federal student loan payments has added pressure — particularly on younger borrowers juggling multiple monthly obligations (NBC Palm Springs, VantageScore).
Loan and payment details
Where payments are largest, delinquencies tend to be worse. LendingTree reports average monthly car payments of $802 in Mississippi, $821 in Louisiana and $867 in Texas — all above the national average of $751. Average loan balances rose by more than $400 year‑over‑year, pushing more borrowers into risky payment territory.
Despite rising delinquencies, total auto loan balances edged down to $1.642 trillion in Q1 2025 — a slight quarter‑over‑quarter decline and only the second such drop since 2011 — suggesting lenders may be tightening standards or fewer consumers are taking on large loans (LendingTree, New York Fed).
Who is most at risk
Younger borrowers and lower‑income households face the biggest risks. Gen Z and millennial delinquency rates are approximately 7.5% and 6.9%, respectively, far above baby boomers’ 1.9% (LendingTree). Late‑stage delinquencies (90+ days), which are the most damaging to credit files and can lead to repossession, have been climbing and are well above pre‑pandemic levels (VantageScore).
Industry and market effects
Rising delinquencies could prompt lenders to tighten underwriting, which would reduce the pool of qualified buyers and could slow dealership sales. Increased repossessions would put downward pressure on used‑car values as repossessed vehicles re‑enter the market. The small decline in total loan balances may be an early sign of credit tightening with potential ripple effects on local economies dependent on vehicle sales and financing.
Investigative look: how policy and personal choices intersect
The 2025 spike reflects both macro policy (higher interest rates) and individual decisions (down payments, loan terms, vehicle choice). Longer loan terms can lower monthly payments but increase total interest and the risk of negative equity. The return of student loan collections has squeezed younger borrowers who often carry both student and auto debt.
“High rates and high prices create a squeeze: households have less margin for error when repairs or unexpected bills hit.”
Implications for Redding, California
Economic impact
Redding is a driving city; most residents depend on personal vehicles. Rising delinquencies can lead to repossessions, reduced consumer spending, and slower sales for local dealerships and repair shops — translating national trends into tangible local stress (LendingTree).
Political consequences
Local leaders may face calls for targeted relief or programs to prevent repossessions. Conservative officials often prefer market‑based solutions, but practical pressures — jobs, cost of living and public‑safety budgets — can make auto debt an active local issue.
Social effects
Vehicle loss risks job instability, missed work, and greater reliance on social services. Younger workers burdened by student loans may delay home purchases or family formation, potentially shifting long‑term community demographics (VantageScore).
Cultural relevance
In a region that values independence and work, repossession carries social stigma. Local faith groups, veterans’ organizations and nonprofits may see rising demand for short‑term aid to help residents bridge missed payments.
Practical applications for residents
- Check loan terms: Review interest rate, loan length and refinance if a better rate is available and sensible.
- Prioritize payments: Given the reliance on vehicles, prioritize car payments in tight months where possible.
- Talk to lenders early: Lenders sometimes offer short‑term plans or modifications to avoid repossession.
- Seek free counseling: Local credit counselors and nonprofits can help restructure budgets and negotiate with lenders.
- Maintain emergency savings: Even small buffers reduce the risk of missed payments after an unexpected repair or bill.
Sources and further reading
Primary sources and reporting cited in this article:
- LendingTree: Delinquency Rates Study
- VantageScore: CreditGauge report on auto delinquencies
- NBC Palm Springs: reporting on rising car payment delinquencies
- New York Fed: consumer credit topics and auto loans
- AOL: background on long‑term trends in auto loan delinquencies
For Redding residents: community credit unions and local nonprofit counselors can help review options and reduce the risk of repossession. The national rise in auto loan delinquencies in 2025 is a warning sign — and a prompt for practical, protective steps to preserve jobs, families and businesses.