Obamacare premiums set to spike in 2026 — 24 million Americans face steep hikes unless Congress acts
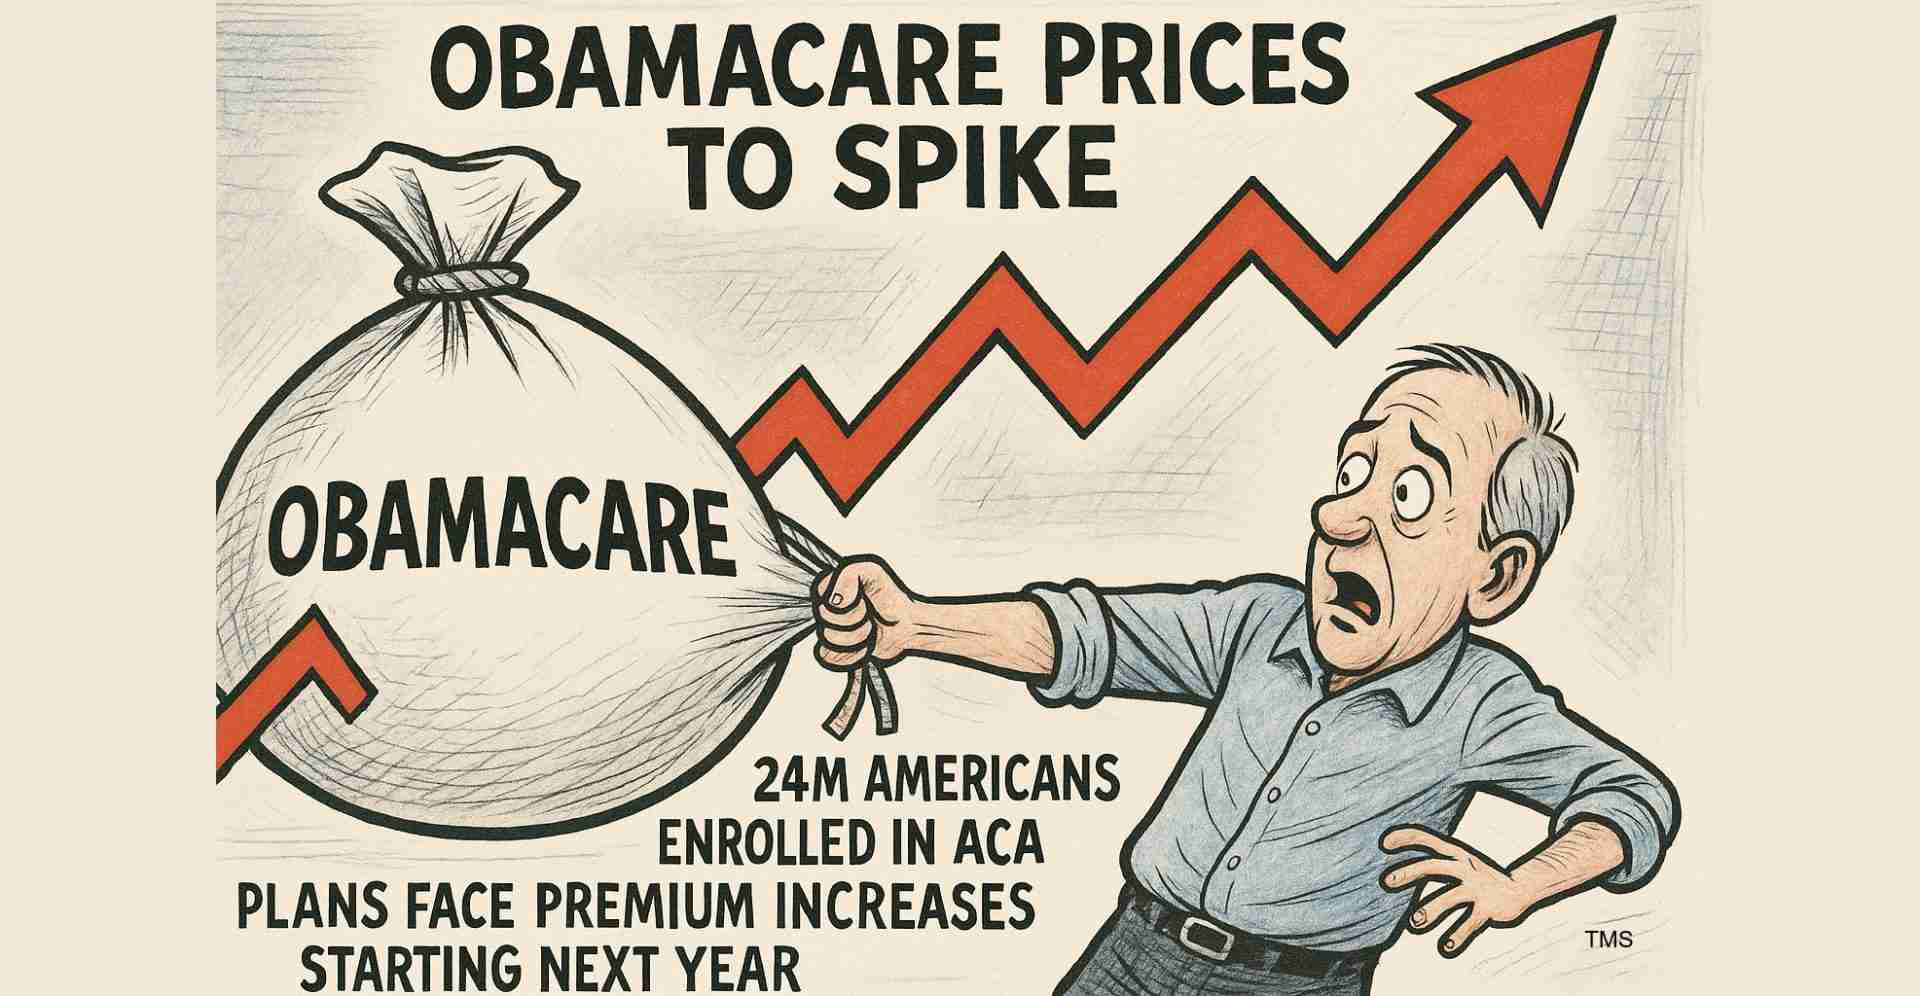
Obamacare premiums are expected to jump an average of 26% in 2026 as enhanced premium tax credits expire, potentially affecting roughly 24 million marketplace enrollees and driving sharp monthly cost increases unless Congress renews the subsidies.
Key takeaways
- Average premiums: Insurers propose about a 26% nationwide increase for 2026 — roughly 30% on Healthcare.gov states and 17% in state-run exchanges, per KFF.
- Millions at risk: Around 24 million Americans enrolled in ACA plans could face large hikes if enhanced premium tax credits lapse, according to Time and KFF.
- Cost shock: If enhanced credits expire, average monthly payments for subsidized enrollees could more than double — KFF estimates roughly a 114% increase in payments (KFF analysis).
Key information
Insurer filings and government estimates point to a steep rise in 2026 marketplace premiums. Proposed increases average about 26%, with federal exchange states seeing larger jumps. Policy decisions on the enhanced premium tax credits are the principal determinant of what households ultimately pay.
- Average marketplace premiums projected to rise ~26% in 2026; states on Healthcare.gov roughly 30% and state-run exchanges about 17% (KFF).
- About 24 million Americans enrolled in ACA plans could face higher costs if Congress does not act (Time; KFF).
- The main driver is the scheduled expiration of the enhanced premium tax credits that were expanded during the pandemic and partly renewed — expiration would return credits toward pre-pandemic levels (Time; KFF).
- If enhanced subsidies lapse, average premium payments for those who lose the extra credits could rise ~114% on average (KFF analysis).
- The Centers for Medicare & Medicaid Services projects that, with subsidies extended, the average premium for the lowest-cost plan on HealthCare.gov could be about $50 per month for eligible enrollees (CMS).
Why prices are set to rise: the mechanics
Expiration of enhanced premium tax credits
Temporary pandemic-era increases to ACA premium tax credits were designed to lower monthly costs during the COVID emergency. Those boosts are scheduled to end after 2025 unless Congress acts, which would leave many families paying far larger shares of premiums. The tax-credit size is tied to income and benchmark plan costs; reverting to pre-pandemic levels would expose middle-income households to insurer price increases (Time; KFF).
Insurer rate increases and healthcare inflation
Insurers have proposed rate hikes averaging 26% nationwide as they account for rising costs in hospitals, prescription drugs, and medical services. States using the federal platform generally face larger increases (~30%), while state-run exchanges average nearer 17% (KFF; Fox Business).
Who will be hit hardest
- Subsidized enrollees: Roughly 22 million of the ~24 million ACA enrollees currently receive some subsidy; many could see monthly premiums more than double if enhanced credits end (KFF).
- Middle-income families: Households too high to qualify under a reverted formula would face full price increases — often working families, small-business owners, and farmers.
- Geographic variance: Consumers in states relying on the federal Healthcare.gov platform are likely to see bigger increases than those in state-run exchanges (KFF).
Political fight and budget pressure
Enhanced credits are a central bargaining chip in budget negotiations on Capitol Hill. Democrats generally push to renew the subsidies to prevent sudden cost increases; some Republicans resist extension for fiscal reasons and concerns about long-term program costs (Time).
“The dispute over these credits has fed broader budget standoffs and been tied to past shutdown threats,” analysts note.
Other contributing factors and examples
Changes in credit calculations will increase the enrollee share of premiums for many. Illustrative reporting shows families in some states could face dramatic jumps in both deductibles and monthly premiums if enhanced credits lapse (Time).
Projected costs for 2026 and federal estimates
With subsidies extended: CMS projects the average premium for the lowest-cost plan on HealthCare.gov could be about $50 per month for eligible enrollees in 2026 (CMS).
Without congressional action: Many enrollees will face much higher out-of-pocket costs; KFF estimates average subsidized enrollee payments could more than double (KFF analysis).
Implications for Redding, California
Economic impact
Many Redding-area residents work in small businesses, construction, agriculture, or service industries. A sharp rise in Obamacare premiums would hit household budgets: middle-income families who lose subsidies could face hundreds more per month or higher deductibles, reducing disposable income and slowing local spending in Shasta County.
Local healthcare providers and county budgets
If premiums and out-of-pocket costs rise, some residents may drop coverage or delay care, increasing uncompensated care at institutions such as Mercy Medical Center Redding. More uninsured patients can drive cost-shifting that stresses local hospitals and clinics.
Small businesses and employers
Small employers who assist workers with insurance — or who feel labor-market shifts — may face hiring and retention challenges. Rising healthcare costs can make benefits unaffordable for firms with thin margins, potentially slowing hiring or increasing wage pressure.
Political consequences and local leaders
Redding voters, many of whom emphasize fiscal discipline, may press Congress for reforms that lower long-term costs rather than open-ended subsidy extensions. At the same time, residents will demand relief from steep premium hikes, putting local elected officials under pressure to find practical solutions.
Social effects and community wellbeing
Higher premiums and deductibles could force families to choose between medical care and essentials. Rural residents and older adults in the Redding area may be particularly vulnerable; community groups and faith-based organizations could see increased demand for assistance.
Cultural relevance and practical actions for residents
In a community valuing self-reliance, many residents will prefer policies that lower healthcare costs long term. Practical steps now include:
- Shop marketplace plans carefully during open enrollment.
- Check eligibility for subsidies or cost-sharing reductions.
- Consult county health offices for assistance and resources (CMS guidance).
- Small-business owners should review benefits strategies and consult brokers about alternatives and cost controls.
Sources
- KFF: ACA insurers are raising premiums by an estimated 26%
- KFF analysis: Marketplace premium payments would more than double if enhanced credits expire
- Time: ACA premium tax credit expiration story
- Fox Business: coverage of premium increases
- CMS fact sheet: Plan year 2026 marketplace plans and prices
- Additional reporting (AOL summary)